Revenue from Contracts with Customers
Book the right revenue, at the right time.
Nine modules: the five steps, the special topics and the IFRS 18 outputs.
- Free launch accessenrol free while we open
- About 39.5 hoursstudy time (estimate)
- Certificateof completion + transcript
By enrolling you accept the Terms. See the Privacy Policy.
Your path to a certificate
Pick a module, then an outcome
See a real extract from this module
From the course: when does revenue arise?
Clearflow Pumps (fictional, Brazil) delivers an irrigation pump to a farm on 30 June. The farm accepts it, starts using it and decides how it is used. The invoice is CU 9,000, payable 60 days later. Clearflow's year ends on 31 July.
| Trade receivables | CU 9,000 |
| Revenue (operating category) | CU 9,000 |
| Revenue: irrigation pumps, point in time | CU 9,000 |
See a real extract from this module
From the course: a spoken order
Spicetrail Spices (India) has supplied spices to the Asha Grocers chain for four years on telephone orders, with the same price list and 30-day terms. On Monday the chain phones in its usual order, worth CU 9,600, and it is delivered the same day. Nothing is signed.
| Trade receivables | CU 9,600 |
| Revenue (operating category) | CU 9,600 |
| Revenue: spoken-order sales, point in time | CU 9,600 |
See a real extract from this module
From the course: a functional link only
Upland Pump Supplies sells a solar pump (CU 12,000) to a farm with one box of 50 filter cartridges (CU 2,000), each at its usual price. Both are delivered in the year and the farm pays on delivery. The pump cannot run without a cartridge. Upland also sells cartridges on their own to other pump owners, and the cartridges do not change the pump.
| Cash and cash equivalents | CU 14,000 |
| Revenue (operating category) | CU 14,000 |
| Revenue: pumps | CU 12,000 |
| Revenue: filter cartridges | CU 2,000 |
See a real extract from this module
From the course: shares as payment
Danube Software Labs performs services and is paid in 5,000 shares of its client. A fair value of CU 16 a share can be estimated. The usual price of the services is CU 90,000.
| Shares received, at fair value | CU 80,000 |
| Revenue (operating category) | CU 80,000 |
| Fair value of shares received (5,000 x CU 16) | CU 80,000 |
See a real extract from this module
From the course: Worked example (E2): discount for some items only
Deskmate Office Supplies sells a printer (A), a toner pack (B) and a service plan (C) together for CU 10,000. It regularly sells each alone: A CU 4,000, B CU 5,500, C CU 4,500. It also regularly sells B and C together for CU 6,000.
| Revenue: printer (A), when delivered | CU 4,000 |
| Revenue: toner pack (B), when delivered | CU 3,300 |
| Revenue: service plan (C), as the plan is delivered | CU 2,700 |
| Total revenue once all items are satisfied | CU 10,000 |
| Operating profit (revenue only in this extract) | CU 10,000 |
| Discount allocated wholly to the toner pack and service plan | CU 4,000 |
See a real extract from this module
From the course: an indicator check
Northwood Joinery sells an office desk set to a law firm for CU 18,000. On 3 June the firm collects the desks and moves them into its offices. Title passes at collection, the invoice is payable within 30 days, and from that day any damage is the firm's loss. The firm has no right to return the desks and Northwood has nothing else to deliver.
| Trade receivables | CU 18,000 |
| Revenue (operating category) | CU 18,000 |
| Revenue recognised at a point in time | CU 18,000 |
See a real extract from this module
From the course: a loyalty voucher as a material right
Penrose Appliances sells 100 washing machines at CU 900 each, the price it charges when selling them alone. It gives each customer a voucher for CU 150 off a future purchase. Non-customers cannot get the voucher. Penrose expects 40% of vouchers to be used. Customers pay in cash.
| Contract liability for vouchers | CU 5,625 |
| Revenue: machines | CU 84,375 |
| Revenue recognised at a point in time | CU 84,375 |
| Contract liability for vouchers | CU 5,625 |
See a real extract from this module
From the course: Worked example (E13): remaining performance obligations
At 31 December 20X5: C1 has 18 months of maintenance left at CU 1,125 a month. C2 has CU 125,000 of price not yet earned (500,000 less 375,000), all expected in 20X6, plus the constrained bonus of CU 20,000. C3 has CU 45,000 of subscription left and was expected at the start to last 12 months.
| Expected to be recognised within 1 year | 138,500 |
| Expected to be recognised in 1 to 2 years | 6,750 |
| Total remaining performance obligations | 145,250 |
| Left out by the short-contract expedient (subscriptions) | 45,000 |
| Left out because constrained (C2 bonus) | 20,000 |
See a real extract from this module
From the course: compensation for flight delays
Northstar Air sells tickets worth CU 600,000 for flights flown in March, with cash received in March. Its terms give passengers cash compensation when a flight arrives more than three hours late. From its history, Northstar expects to pay CU 18,000 for March flights.
| Liability for expected passenger compensation | CU 18,000 |
| Revenue: passenger transport (operating category) | CU 582,000 |
| Ticket sales before compensation | CU 600,000 |
| Variable consideration: expected compensation | (18,000) |
| Revenue recognised | CU 582,000 |
Test yourself on IFRS 15 now
Instantly marked. Practice only.
Learning outcome M4-LO5Measure non-cash payments received and amounts paid back to customers, and show how each changes revenue.Measure non-cash and customer payments
Tallinn Data Services completes a project for a client and is paid in 12,000 shares of the client. The fair value of the shares can be reasonably estimated at CU 6.50 a share. The usual stand-alone price of the services is CU 90,000.
Learning outcome M4-LO2Estimate variable consideration with the expected value or most likely amount method, choosing the one that better predicts the entitlement.Estimate variable consideration
Verona Printing signs one contract with a fixed fee of CU 500,000 and a bonus of CU 60,000 if it delivers by 30 June. The bonus is either earned in full or not at all, and Verona Printing judges that earning it has a 70% chance. Assume the constraint does not limit the amount.
Type a number only. Digits only, no commas or currency symbols.
Learning outcome M6-LO1Explain control and the indicators that show the moment a customer gains a good or service.Explain control and its indicators
A finance clerk at a distributor is listing the signs that control of delivered goods has moved to the customer at a single moment.
Select TWO answers. All must be right.
Email me my result and the one-page cheat sheet
Turn on JavaScript to check your answers instantly. Or download the one-page cheat sheet (PDF).
Revenue is where judgement meets the numbers
- One module per step with a mini-case and worked examples
- See the outputs every example ends in an IFRS 18 extract
- The hard cases too principal or agent, licences, warranties, costs
Who it is for: pick your role
Prepare the entries, contract balances and revenue notes, and update the revenue policy.
Test the five-step judgements, cut-off and disclosures, and challenge a generic revenue note.
Price and structure contracts knowing how the revenue will land in the numbers.
What happens after you enrol
- EnrolA short form, about a minute.
- You are inStraight into the course, logged in.
- StudyNine modules at your own pace.
- CertificateWith a transcript of your results.
How you are assessed, and what you receive
- Learn9 modules: notes, slides, workbook
- Check20-question knowledge check per module, pass 60%, unlimited attempts, instant feedback
- ApplyA short deliverable per module
- PractiseRevision quizzes by step and 2 timed practice exams
- ProveCapstone case and the Competence Check (objective test, workplace cases, portfolio)
- ReceiveCertificate of completion and transcript
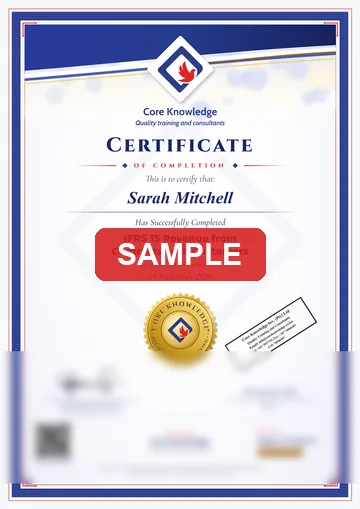
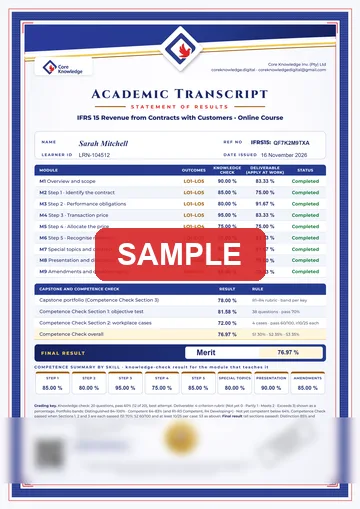
Your certificate and transcript
- Page 1: Certificate of Completion, issued by Core Knowledge, with a verification code.
- Page 2: transcript with your knowledge-check result for every module, your Competence Check results and your result band.
- It confirms completion of a Core Knowledge course; it is not an accreditation or a CPD-hours statement.
Samples: names and figures are illustrative.
Questions, answered
When do I get my certificate?
When you have passed the knowledge check in every module (60 percent or more), submitted each module deliverable, and completed the capstone case and the Competence Check. Your Certificate of Completion and transcript, issued by Core Knowledge, then become available in the course. It confirms completion of a Core Knowledge course; it is not an accreditation or a CPD-hours statement.
How much does it cost?
Nothing while we open. Launch access: enrol free while we open; pricing announced later. Launch access includes the Online Study Course, the Online Practice Questions inside it, and the Certificate of Completion and transcript when you complete the course. To enrol a team, ask us.
How long does it take?
About 39.5 hours of study in total, across 9 modules and a capstone case. This is an estimate for planning only and not a CPD-hours statement; your time depends on your experience with revenue contracts.
How do I pay?
There is nothing to pay while we open: enrolment is free and the enrol form has no payment step. Pricing will be announced later.
When can I start?
Any time. Fill in the short enrol form and you land in the course a few seconds later, already logged in. Your username and password arrive by email so you can log in again from any device.
What is included?
The Online Study Course (9 modules with learning outcomes, infographics, slides, learner notes, workbooks and deliverables, plus the capstone case) and the Online Practice Questions: a 20-question knowledge check in every module (180 questions in all), revision quizzes by step and two timed practice exams.
What devices can I use?
Any up-to-date web browser on a computer, tablet or phone, with an internet connection. A computer or tablet is easier for the number-entry questions and the deliverables.
Independent material in our own words · IFRS as issued, CU examples · paragraph references on every outcome · worked examples with statement extracts.
Last verified: 25 Oct 2026 against IFRS 15 as issued (with the 2016 Clarifications). Standards watch: changes since 2014 are in Module 9 (see the module).
Independent learning material prepared by Core Knowledge. Not affiliated with or endorsed by the IFRS Foundation or the IASB. Paragraph references are to the published standards.